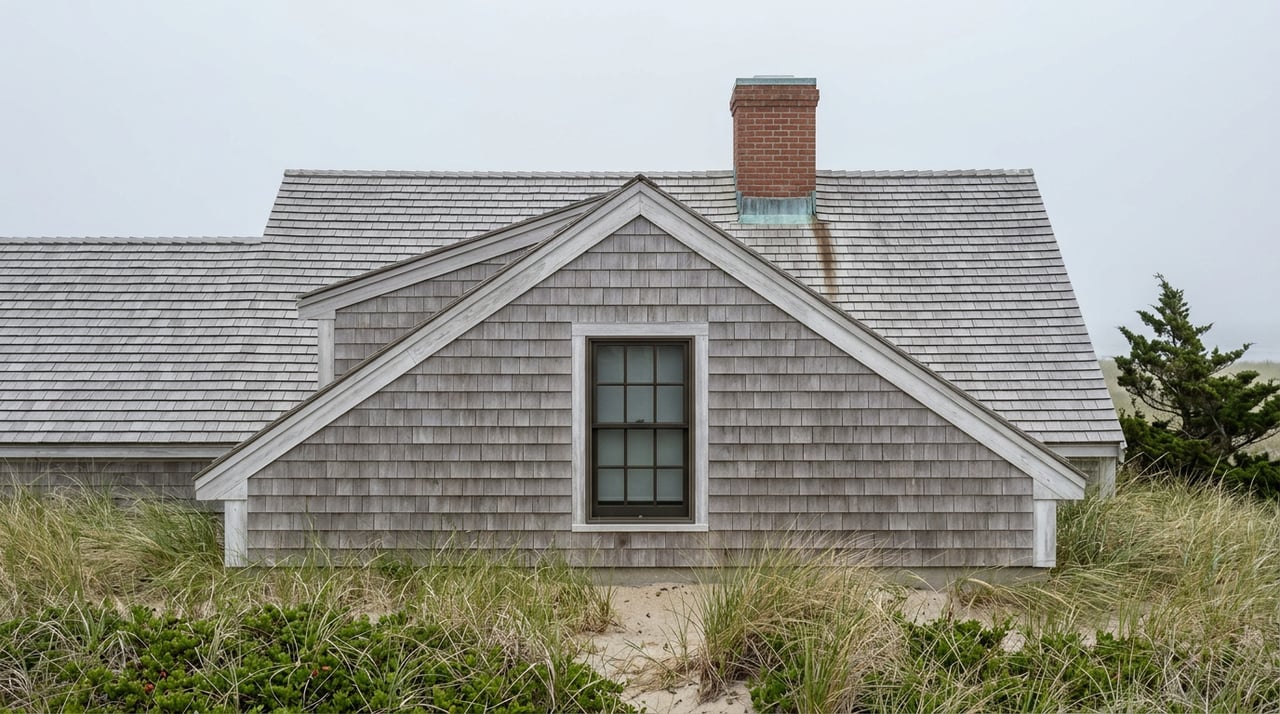
The Hamptons Median Just Hit a Record. Here's What That Number Isn't Telling You
September 24, 2026
September 24, 2026
In March, an oceanfront estate on nearly four acres in East Hampton sold for $72 million. It had spent time on the market asking $120 million. The property carried real history: Ann Tenenbaum and her late husband, private equity investor Thomas H. Lee, bought it from Lee Radziwill and her husband, director Herbert Ross, for $16.2 million back in 2001. Three brokers worked the deal to the finish, Preston Kaye of Hedgerow Exclusive Properties, Adam Modlin of the Modlin Group, and Terry Cohen of Compass. The sale became this year's cautionary tale on the South Fork: even a trophy has to meet the market somewhere.
That $48 million gap between ask and close is worth sitting with, because it says something the headline Hamptons numbers this year don't. Every market report from the past two quarters points to the same fact: the median sale price out here has never been higher. What most of those reports leave out is how a market can post a record median while actually selling fewer homes than it did a year ago.
At the end of the second quarter of 2026, the median Hamptons sale price stood at $2.4 million, up 24% from the same point in 2025, according to William Raveis market data cited by The Real Deal. Go back further and the pattern holds: the median crossed $2 million for the first time ever during the first quarter of 2026, per figures from Douglas Elliman and appraiser Jonathan Miller. Sales above $5 million made up a record 21.2% share of transactions during that same stretch.
Read quickly, that's a market on fire. Read closely, it's a market getting smaller at the bottom and bigger at the top at the same time.
Here's where the story gets interesting for anyone actually shopping this fall rather than just watching headlines. A broader market tracker covering more modestly priced sales across the same towns put the three-month median through August 2026 at $1.4 million, up only 1.8% year over year. Price per square foot in that same window actually fell 6.7% compared to a year earlier, and homes took an average of 90 days to sell, up from 77 days the year before.
Two legitimate data sets, covering the same geography, arriving at medians roughly a million dollars apart. Neither is wrong. They're measuring different Hamptons.
| Measure | Luxury-weighted tracker (Q1–Q2 2026) | Broader tracker (3 months through Aug. 2026) |
|---|---|---|
| Median sale price | $2.0M–$2.4M | $1.4M |
| Direction vs. prior year | Up 24% | Up 1.8% |
| Price per square foot | Not broken out | Down 6.7% |
| Days on market | Not broken out | 90, up from 77 |
The luxury-weighted number is climbing because a shrinking pool of sales is skewing toward the top. The broader number is nearly flat because the middle and entry tiers of the market are moving slowly and not gaining much ground on price.
The mechanism is straightforward once you see the deal counts behind it. Over the twelve months from July 2025 to June 2026, home sales across the Hamptons fell even as total dollar volume rose 13.6%. During that stretch, deals at $10 million or more climbed 24%, from 90 to 112. Deals under $2 million fell 20%.
That's the whole trick. When the cheap end of the market thins out and the expensive end holds steady or grows, the median rises even if fewer total transactions are closing. It isn't that more people are buying at higher prices. It's that the buyers who remain are concentrated at the top.
Cody Vichinsky of Bespoke Real Estate, who topped The Real Deal's 2026 ranking of Hamptons brokers based on closed sales over $500,000 between June 2025 and June 2026, put it plainly: today's sellers aren't chasing broad market efficiency, they're waiting for the one buyer who wants exactly what they have. Preston Kaye of Hedgerow described it as a widening gap between great inventory and everything else, with buyers willing to stretch for a property they consider exceptional and walking away from anything that isn't.
The most recent weekly data backs this up in real time. In the week ending September 8, 2026, 28 listings went into contract across the Hamptons, down 32% from the 41 recorded in the same week of 2025, with dollar volume falling to $129 million from $147 million. The week before, 29 contracts closed, down 6% from 31 a year earlier, though dollar volume that week actually rose to $141 million from $124 million.
Fewer contracts, dollar volume moving in either direction depending on which few deals happened to close that week. That's exactly what a thin, top-heavy market looks like from the inside.
None of this means the fall market is quiet. Brokers interviewed by Spark Hamptons in September described the opposite: the buyers showing up after Labor Day tend to be serious, informed, and ready to move, in contrast to the lookers who filled open houses in July and August. About half of Hamptons deals still close in cash, and even financed buyers frequently waive the mortgage contingency to keep their offer competitive. As mortgage broker Melissa Cohn is fond of telling her clients, "Marry the house and date the mortgage rate." The idea being that you can always refinance later, but you can't go back and buy the house someone else closed on.
If the top of the market is where the headline number lives, the value is still findable elsewhere on the East End. Brokers point to Springs, Hampton Bays, and North Sea as places where a given budget stretches further and buyers face less competition than in East Hampton, Southampton, or Sag Harbor village proper. Some buyers, wary of summer traffic further east, are also looking at Westhampton and East Quogue. None of these are secrets, but they matter more now than they did two years ago, because the gap between the trophy tier and everything else has only widened.
If you're comparing the Hamptons to other markets using a single median figure, ask which slice of the market that number actually describes. A $2.4 million median tells you almost nothing about what a three-bedroom house in Hampton Bays will cost this fall. A $1.4 million median tells you almost nothing about how a waterfront estate in East Hampton will be priced or negotiated. Both are true. Neither is the whole picture.
For sellers, the lesson from the Tenenbaum sale and the broader data is the same: pricing to the top of the market invites a long, public negotiation down. For buyers, it means the properties getting bid up are concentrated in a narrow band, and there's real room to negotiate everywhere else, especially on homes that have sat since summer.
Does a rising median mean now is a bad time to buy? Not necessarily. It means the buyers you're competing with in the top tier are more motivated than the headline suggests, while the broader market has more room to negotiate than the same headline implies.
Should sellers still price at a premium? The Tenenbaum estate closed at 40% below its original ask. That's not a sign that pricing high never works, but it is a reminder that even trophy properties eventually meet the market's actual ceiling rather than the seller's opening number.
Why do different reports show such different median prices for the same region? Because they're built from different pools of sales. A tracker weighted toward luxury closings will show a much higher median than one that captures the full range of Hamptons transactions, even when both are accurate for what they measure.
Numbers like these are only useful when you know exactly what they're counting. That's the work we do with every buyer and seller we represent across the East End, translating headline data into the specific number that applies to the property and the timeline in front of you. If you're weighing a move in the Hamptons this fall, The Saez + Fromm Team would welcome the chance to talk it through. Request a Private Consultation whenever you're ready.
Stay up to date on the latest real estate trends.
September 24, 2026
September 17, 2026
September 10, 2026
September 3, 2026
August 27, 2026
August 20, 2026
August 13, 2026
August 13, 2026
August 6, 2026
As a top team at Douglas Elliman, SAEZFROMM continues to deliver the greatest value to our buyers, sellers, developers, and investors. Our focus is on one thing above all others: our clients, their needs, and what makes them happy.
SAEZFROMM
M: (212) 203-1798
O: (212) 891-7181
[email protected]
Douglas Elliman Real Estate
140 Franklin St
New York NY 10013